If your Series A pitch deck looks like your seed deck with updated traction numbers, you probably have the wrong deck.
The company may still have the same founders, product, and long-term vision, but the investment case has changed. At seed, investors are trying to understand whether you have found something worth building: a real problem, a credible insight, early demand, and a team that might turn it into a large company. By Series A, the question becomes more specific. Investors want to know whether what you have built is starting to become repeatable.
You have had more time, more customers, and usually more capital to test the assumptions from your previous round. The deck should reflect what you learned during that period and whether you have a repeatable playbook to scale the business. That is why a Series A pitch deck is not simply a seed deck with stronger numbers or more charts. The narrative itself needs to mature.
Seed is about evidence. Series A is about scaling.
A seed-stage company is allowed to have unanswered questions. Pricing may still be changing, the GTM motion may still depend heavily on the founders, and the ICP may still be narrowing. Some parts of the business model are still hypotheses, so the deck needs to show that those hypotheses are becoming more believable through real customer behavior.
That evidence can take different forms. Maybe ten customers are using the product in a similar way. Maybe a pilot has produced a measurable result. Maybe one customer segment is converting significantly faster than the others. Maybe early retention suggests that the pain is stronger than the founders initially expected.
At Series A, the bar moves. Investors are no longer looking only for signs that something works. They want to understand why it works, whether it happens consistently, and what is likely to happen when the company puts more capital behind it. This is the core shift in the story: from early validation to repeatability.
Traction needs to explain what the numbers mean
At seed, relatively small traction can still be powerful if it proves an important assumption. A handful of paying customers may be enough to validate that a specific buyer has a real problem. A successful pilot can show that the product creates measurable value. Strong organic usage may suggest that customers are pulling the product into the market rather than being pushed into it.
At Series A, simply showing that the numbers went up is not enough. Investors start asking what sits behind that growth. Are customers coming from the same ICP? Are they buying for the same reason? Are they staying? Are contracts expanding? How long does it take to close them? Is revenue distributed across the customer base, or does one account make up a large share?
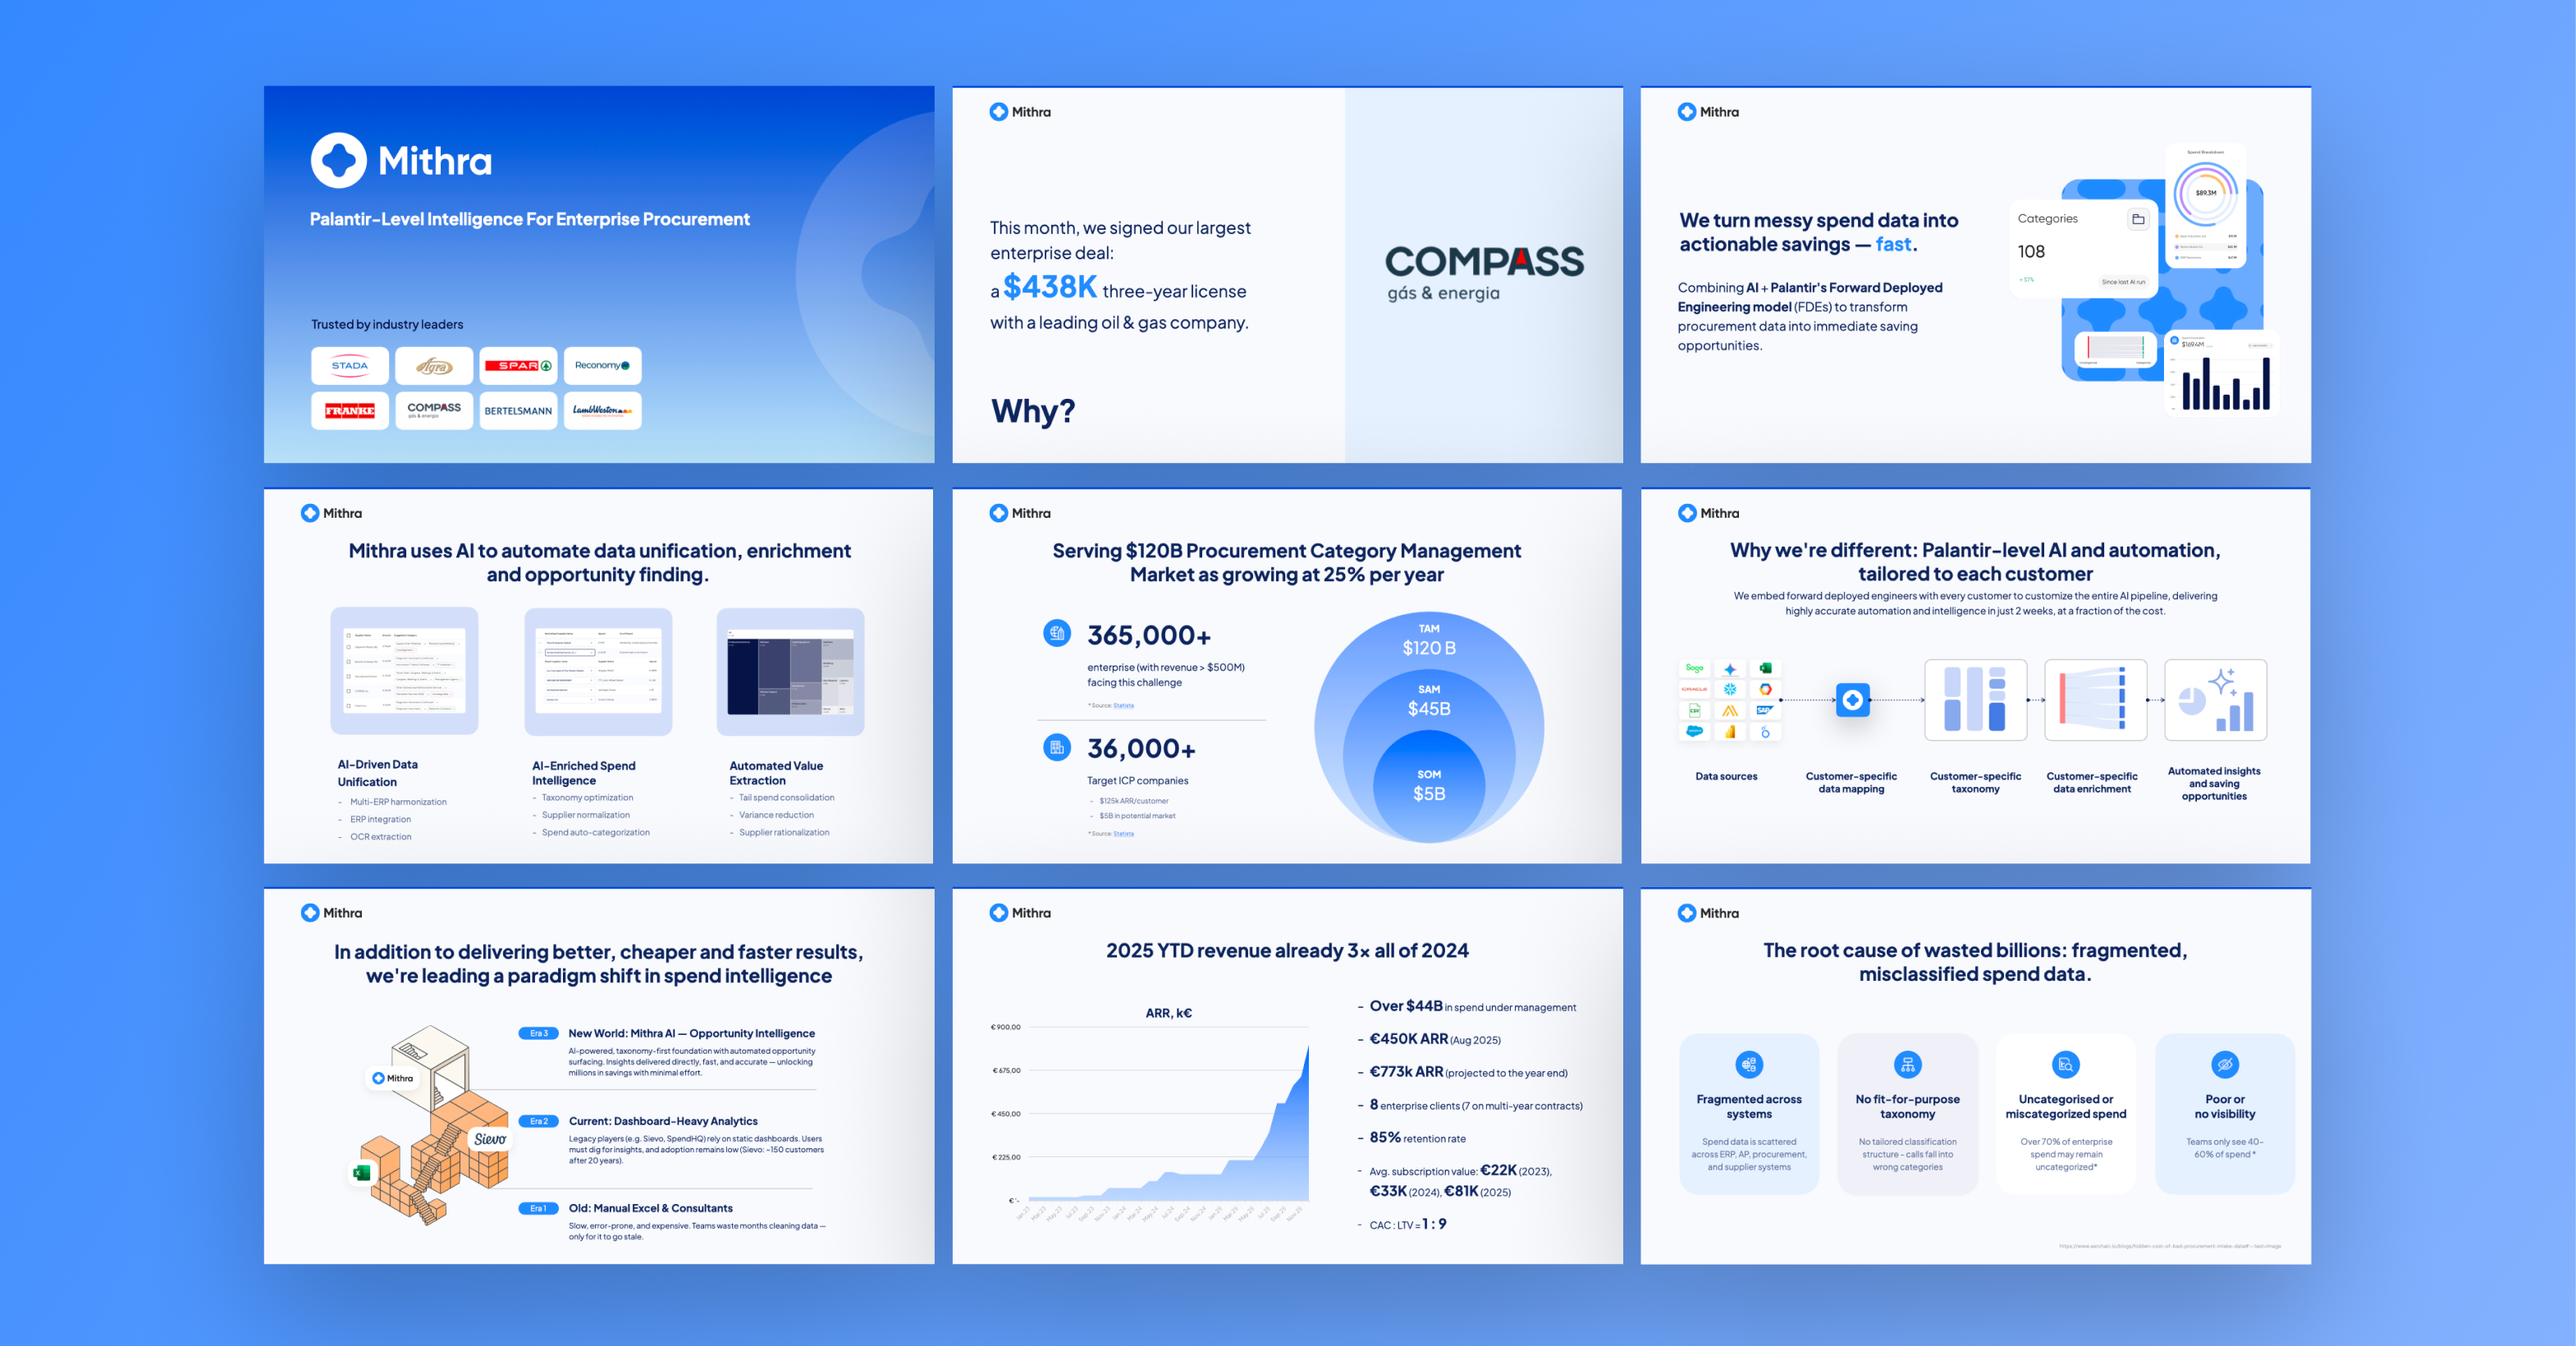
The traction slide therefore becomes less about showing momentum and more about explaining the quality of that momentum. A chart showing ARR growing from $100K to $2M is useful. A chart that also helps the investor understand who is buying, how consistently they retain, and why the growth is becoming more repeatable tells a much stronger Series A story.
The market slide should show where growth comes from
At seed, the market slide often has one main job: prove that the opportunity is large enough to support a venture-scale business. A bottom-up market model is usually more useful than a broad industry statistic because it connects the number to real customers and realistic contract values.
At Series A, that is no longer enough. Investors already expect the market to be large. What becomes more interesting is the path from the customers you have today to the larger opportunity you keep talking about.
If the company started with mid-sized logistics operators, for example, what happens next? Do you move into enterprise? Add more products for the same accounts? Expand geographically? Use the current segment as a wedge into a broader category?
This is where many Series A decks still feel like seed decks. They show a huge TAM, but nothing in the narrative explains how the current business grows into it. The market slide should make that expansion path visible.
GTM moves from plan to evidence
Founder-led sales is completely normal at seed. In fact, it is often useful because the founders stay close to customers and learn why they buy, what objections appear, which features matter, and how the sales process actually works.
By Series A, though, “we will raise capital, hire more salespeople, and grow faster” is not a GTM strategy. Investors want to understand what the company already knows about acquisition. Who is the buyer? How long is the sales cycle? Which channel produces the best customers? Where does the founder still sit in the process? What happens when another salesperson is added?
You do not need to have GTM completely solved, but you should be able to show that it is becoming understandable. There is a big difference between “we know how to sell this ourselves” and “we are starting to understand how to build a repeatable sales engine.” That difference belongs in the deck.
Assumptions should start turning into actual economics
At seed, a business model slide often contains assumptions. The company may expect an annual contract of $20K, margins of 80%, or expansion revenue over time. That is reasonable when operating history is still limited.
By Series A, investors can compare those assumptions with reality. What is the actual ACV? How long does it take to close a customer? Are existing accounts expanding? What does gross margin look like today? Which assumptions from the seed round proved correct, and which ones did not?
This does not mean every Series A company needs perfect economics. Many are still investing heavily in growth. But the deck should clearly distinguish between what the team believes and what the business has already demonstrated. That distinction makes the story much more credible.
The ask should connect capital to something that already works
“We are raising $8M to scale” is one of the weakest ways to end a Series A deck because it leaves the obvious question unanswered: scale what?
At seed, capital is often used to remove fundamental uncertainty - finish the product, validate demand, prove a sales channel, or reach a meaningful revenue milestone. By Series A, some of those risks should already be reduced. The new round is usually about accelerating something that has begun to work while solving the next constraint on growth.
If one sales team has reached a repeatable level of productivity, maybe the round funds expansion into another region. If customers consistently expand after six months, perhaps the capital is used to develop additional products for the same accounts. If a particular acquisition channel has become predictable, the raise may allow the company to scale it faster.
The use of funds should connect the evidence already shown in the deck with the next stage of the business. That is much more convincing than a generic pie chart with percentages for sales, product, and marketing.
Design expectations change at Series A too

At seed, investors may be more forgiving of a deck that looks relatively simple or founder-made, especially when the company is still early and the main thing being evaluated is the insight behind the business. By Series A, that tolerance is much lower. The company has grown, the round is larger, and the presentation is expected to reflect the level the business has reached.
This does not mean a Series A deck needs to look expensive for the sake of it. It means the quality of the presentation should match the quality of the company behind it. The visual system, hierarchy, charts, product screens, and overall consistency should make the business feel mature and make complex information easier to understand. Investors are evaluating not only the opportunity, but also how clearly and professionally the company communicates it.
We often see this transition with founders who built their pre-seed or seed deck themselves. That can work perfectly well at an earlier stage. But by Series A, they usually realize that the same deck no longer represents the company they have become. The business has changed, the expectations have changed, and the presentation needs to catch up.
Do not update your seed deck. Rebuild the argument.
When founders prepare for a new round, the easiest thing to do is open the old deck and start replacing numbers: new ARR, new customer logos, new hires, bigger raise.
It is also one of the easiest ways to end up with the wrong Series A deck.
Before changing anything, go back to the story you used at seed and ask what you wanted investors to believe at that point. Then compare it with what actually happened. Which assumptions were right? Which were wrong? What did customers teach you? Which segment turned out to matter most? What part of the GTM model is beginning to repeat? What is now proven that used to be only a hypothesis?
Your new deck should be built around those answers.
At seed, the story may have been:
We see an important problem differently, and early customers are validating our approach.
At Series A, it may become:
We turned that insight into a business model that is starting to repeat, and this round allows us to scale what is working.
Same company. Same vision. Different investment case.
If you are preparing for a Series A and your deck still feels too close to the one you used at seed, book a free intro call with 100PitchDecks. We can help identify what the new investment story needs to prove before it moves into design.
Artem Pochepetsky is the founder of 100PitchDecks and a pitch deck strategist working with founders across pre-seed, seed, and Series A.